Best Tax Saving Mutual Funds – What is ELSS and How to Invest in It?
Tax saving mutual funds: when we mention them, usually what people would mention is equity-linked savings schemes, or ELSS. These schemes let you invest money in stock markets, with a tax break up to Rs 1.5 lakh under section 80C. And this investment is for three years only – PPF funds money for 15 years; even a tax-saving fixed deposit would invest the money for five years. This blog covers what ELSS actually involves and how someone can start investing in it. What Exactly Are Tax Saving Mutual Funds? At their core, these are equity mutual funds that also qualify for a tax deduction, which is what separates them from a regular equity fund. A fund manager takes money from a large pool of investors and puts most of it into stocks and equity-related instruments. Since these are market-linked, there’s no fixed return promised anywhere, unlike a fixed deposit where the number is locked in from day one. A few things that define Tax Saving Mutual Funds: At least 65% of the portfolio has to sit in equities Three years is the lock-in, the shortest across all 80C instruments Returns move with the market; nothing is guaranteed Can be started as a lump sum or through monthly SIPs Set this against PPF’s fifteen-year commitment or a tax-saving FD’s five years, and ELSS starts looking a lot more attractive for anyone who wants liquidity sooner rather than later. How Do Tax Saving Mutual Funds Actually Work? Once money goes into ELSS, it stays locked for three years while the fund manager actively trades stocks based on where the opportunities are. There’s no early exit here. Even if the market dips hard six months in, the money can’t be pulled out before the three-year mark. Oddly enough, this restriction tends to work in the investor’s favor, since it removes the temptation to panic-sell during a rough patch. Once three years pass, the units are fully redeemable. At that point, an investor can either take the money out or just leave it invested if the fund’s been performing well. What Tax Benefits Do Tax Saving Mutual Funds Offer? The headline benefit is a deduction of up to Rs 1.5 lakh under Section 80C, which brings down taxable income for that financial year. This only applies under the old tax regime, though. Anyone who’s switched to the new regime won’t be able to claim this deduction at all, since Section 80C simply doesn’t exist there. Aspect Details Maximum Deduction Up to Rs 1.5 lakh under Section 80C Applicable Regime Old tax regime only Lock-in Period 3 years Tax on Gains After Lock-in 10% LTCG tax above Rs 1 lakh profit Once the three-year lock-in ends, gains get treated as long-term capital gains, and anything above Rs 1 lakh profit in a financial year gets taxed at 10%. How Do Tax Saving Mutual Funds Compare With Other 80C Options? The shorter lock-in is really what sets ELSS apart, along with the fact that it has real growth potential compared to fixed-return instruments. Investment Lock-in Period Average Returns Risk Level ELSS 3 years 12% to 15% High PPF 15 years 7% to 8% Low Tax-Saving FD 5 years 6% to 7% Low NSC 5 years 7% to 7.5% Low Anyone who can handle some volatility usually comes out ahead with ELSS over a long enough timeframe. That said, someone who just wants their capital protected might still lean toward PPF or an FD, and there’s nothing wrong with that choice either. How Can Someone Start Investing in Tax Saving Mutual Funds? It starts with picking a fund, getting KYC done, and deciding whether to go with a lump sum or a SIP. The process doesn’t differ much from investing in any other mutual fund, except there’s one extra thing to check – whether the fund actually qualifies for the tax benefit before putting money in. Here’s roughly how it goes: Complete KYC using PAN, Aadhaar, and bank details Look at how the fund has performed over five to ten years, not just one Pick lump sum or SIP, whichever fits better Invest through an AMC website, an app, or a registered distributor Save the investment proof for filing returns later A SIP tends to work better for people who don’t want to scramble for a lump sum every March. Spreading it across the year makes the whole thing a lot less stressful. Are Tax Saving Mutual Funds Suitable for Beginners? Yes, but only if the investor understands upfront that returns aren’t guaranteed the way they are with PPF or an FD. Starting small through a SIP rather than jumping in with a lump sum makes the whole experience easier to manage. Monthly investments smooth out the highs and lows of the market automatically, so there’s less pressure to time anything perfectly. New investors should also resist picking a fund just because it had one strong year – that’s rarely the full picture. A few things worth checking before investing: How the fund has performed across multiple market cycles, not just a recent good run The expense ratio, since higher fees quietly eat into returns Whether the fund manager has stayed consistent over time Whether a three-year lock-in actually fits your financial plans Pages like r9wealth.com/mutual-fund/tax-saving-mutual-funds carry updated fund comparisons that can help narrow things down before investing. This blog is meant for general understanding only and isn’t financial advice. Talking to a registered financial advisor before investing still makes sense, since everyone’s tax situation looks a little different. Frequently Asked Questions What is the lock-in period for Tax Saving Mutual Funds? ELSS funds carry a mandatory three-year lock-in, the shortest among all Section 80C options. Are Tax Saving Mutual Funds safe for conservative investors? Not really, since these are equity-linked and carry market risk, unlike PPF or fixed deposits. How much tax deduction can be claimed through ELSS? Investors can claim up to Rs 1.5 lakh under Section 80C, but only under the old
HSBC Mutual Fund India 2026 – Best Schemes, Login, and SIP Investment Guide
HSBC Mutual Fund India handles equity, debt, and hybrid schemes through HSBC Asset Management (India) Pvt. Ltd. By late 2025, it had over 190 schemes under management and an AUM close to ₹1,39,633 crore – making it one of the bigger fund houses in the country. Meera, who works in Pune, kept putting off her first SIP for months – not for lack of money, just the confidence to pick a fund house. A colleague mentioned HSBC Mutual Fund India, and within a week, her SIP was up and running. That kind of hesitation is common. The basics aren’t complicated once you sit down and walk through them: logging in, choosing a scheme type, setting up a SIP. What Is HSBC Mutual Fund India? It’s the Indian mutual fund arm of HSBC Asset Management, part of the wider global HSBC Group. Operating here since 2002, it grew considerably after picking up L&T Mutual Fund in 2022. Schemes span equity, debt, hybrid, and tax-saving categories. The scale, plus access to HSBC’s global research network, is a big reason investors in India tend to put it on their shortlist alongside other established AMCs. How Do You Log In to Your HSBC Mutual Fund India Account? Through the official website or app, using your registered email or folio number. New users need KYC sorted first before full account access opens up. Once inside, here’s roughly what’s available: Portfolio view and current NAV Statement downloads SIP start, pause, or modification Redemption requests KYC status check Invested via a third-party platform? Most let you manage your HSBC Mutual Fund India holdings from there too. What Are the Best Scheme Categories Under HSBC Mutual Fund India? There isn’t really a single “best” scheme – it comes down to your goal, how long you’re investing for, and the risk you’re comfortable carrying. Still, HSBC Mutual Fund India’s offerings fall into a few broad categories worth knowing before you choose. Category Risk Level Typically Suited For Equity Funds High Long-term wealth creation Debt Funds Low to Moderate Short-term stability Hybrid Funds Moderate Balanced growth and safety ELSS (Tax Saver) High Tax-saving under Section 80C Before shortlisting anything, check expense ratios and 3- to 5-year returns against the benchmark. Doing just this filters out plenty of weaker choices fairly quickly. How Does SIP Investment Work in HSBC Mutual Fund India? You commit a fixed amount at set intervals, and units get allotted at that day’s NAV. It’s investing steadily rather than guessing when the market will dip – most retail investors aren’t particularly good at that second part anyway. Setting one up means: Completing KYC, if that’s not already done Picking a scheme that fits your goal Choosing the SIP amount and frequency Linking a bank account for auto-debit Confirming it Raise it, pause it, stop it – you can do any of that whenever, through the website, the app, or whichever platform you used to invest. What Documents Do You Need to Invest in HSBC Mutual Fund India? KYC paperwork: identity proof, address proof, your PAN card. Without this, the investment simply won’t go through. What typically gets accepted: PAN card Aadhaar or Voter ID for identity Utility bill or passport for address A cancelled cheque for bank verification Most platforms now run this digitally, so it rarely adds more than a few minutes to a first-time investment. How Long Does Redemption Take in HSBC Mutual Fund India? Depends on the scheme. Equity funds usually credit within three working days. Debt and liquid funds tend to be quicker. Liquid fund redemptions can show up in your account within 24 hours – useful if you suddenly need cash. Equity funds, meanwhile, may carry a short-term exit load if redeemed within a year of investing. Is HSBC Mutual Fund India a Good Choice for 2026? That really hinges on whether its scheme categories match what you’re after. No fund house can promise returns, but the scale, SEBI registration, and broad scheme range give HSBC Mutual Fund India a reasonable case alongside other AMCs worth considering. For a closer look at specific schemes and current numbers, R9 Wealth has a detailed breakdown at r9wealth.com. This piece is meant for general information, not financial advice. Mutual fund investments carry market risk, so go through the scheme documents or talk to an advisor before putting money in. Frequently Asked Questions How do I log in to my HSBC Mutual Fund India account? Use your registered email or folio number on the website or app once KYC is complete. What documents are needed to invest? PAN card, identity proof, address proof, and a cancelled cheque for bank verification. Can I start a SIP with a small amount? Yes – several HSBC Mutual Fund India schemes allow SIPs starting from a few hundred rupees. How long does redemption usually take? Roughly three working days for equity funds; liquid funds can be processed within 24 hours. Is HSBC Mutual Fund India suitable for tax saving? Yes, ELSS schemes qualify for tax benefits under Section 80C of the Income Tax Act. Follow us on Instagram, LinkedIn, Facebook and X (Twitter) for the latest mutual fund insights, SIP tips, investment strategies, and personal finance updates.
How to Choose the Best Mutual Fund Based on Financial Goals
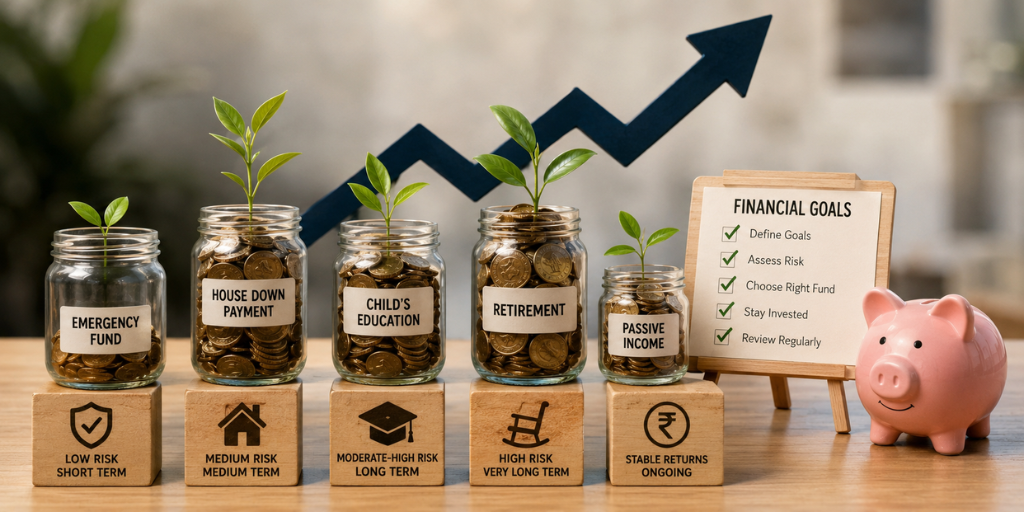
Most people think picking the best mutual fund based on financial goals means finding the one with the highest return. That thinking costs them money. A fund is only good when it fits your goal – not someone else’s portfolio. Amit, a 34-year-old IT professional from Pune, put his house down payment savings into a small cap fund because it was “trending.” Eighteen months later, the market corrected and his corpus dropped 31%. He waited three more years to buy his house. The fund was not bad – his goal and fund simply did not match. What Does It Actually Mean to Choose the Best Mutual Fund Based on Financial Goals? It means picking a fund that suits your timeline, your risk appetite, and the exact purpose of your money – not chasing past returns. A fund giving 22% CAGR sounds great. But if your goal is two years away and that fund needs five years to recover from a bad year, you have already made a mistake. The best mutual fund based on financial goals is always goal-first, fund-second. How Do You Define Your Financial Goals Before Selecting a Fund? Write your goals down before you open any investment app. The best mutual fund based on financial goals cannot work without a clear target to aim at. Split your goals by time: Short-term (under 3 years): Emergency corpus, home appliance, short trip, medical backup Medium-term (3 to 7 years): Car, house down payment, wedding, higher education fees Long-term (7 years and beyond): Retirement, child’s college abroad, generational wealth Each time bucket needs a different fund type. Getting this right is the first real step toward finding the best mutual fund based on financial goals. Which Fund Type Actually Fits Which Goal? Financial Goal Recommended Fund Type Ideal Duration Risk Level Emergency savings Liquid / Overnight Fund Up to 1 year Very Low Short-term parking Ultra Short / Money Market Fund 1–3 years Low Home down payment Hybrid / Balanced Advantage Fund 3–5 years Moderate Child’s education Large Cap / Flexi Cap Equity Fund 7–10 years Moderate-High Retirement planning Diversified Equity + NPS 15–30 years High Passive income need Debt / Monthly Income Plan Ongoing Low-Moderate The best mutual fund based on financial goals sits in the row that matches your actual situation – not the row with the biggest number in the returns column. How Does Risk Tolerance Shape the Best Mutual Fund Based on Financial Goals for You? Two people with the same goal can need different funds, because they sleep differently when markets fall. Risk tolerance is not just a quiz result. It is whether you can watch your portfolio go down 25% and still not touch it. If the answer is no, equity funds will hurt you even if the goal is long-term. Ask yourself honestly: Will I sell in panic if markets drop for 6 months straight? Is this money replacing my salary or growing alongside it? Can I add more when markets fall, or will I freeze? Your answers decide which is the best mutual fund based on financial goals for your personality. Conservative investors should lean toward hybrid and debt funds. Aggressive investors with long timelines do well in equity. Tools on platforms like R9wealth.com help you map your actual risk profile to the right fund category before you invest a single rupee. What Numbers Should You Check When Shortlisting a Fund? The best mutual fund based on financial goals is not just rated five stars. You need to look deeper than that. Check these before you invest: Expense ratio: Below 1% for index funds, below 1.5% for actively managed ones. Higher charges eat into returns silently. Rolling returns over 5 years: A fund that has beaten its benchmark consistently is safer than one with one great year. Fund manager tenure: If the manager changed recently, past performance may not repeat. Exit load period: Matters most for short goals – some funds charge 1% if you exit within a year. Standard deviation: A lower number means less volatility, which matters a lot when your goal is near. The best mutual fund based on financial goals passes all five checks – not just the return test. SIP or Lump Sum – Which Works Better for Goal-Based Investing? The best mutual fund based on financial goals also depends on how you invest, not just what you invest in. SIPs work best for long-term equity goals. They average your cost across market cycles and remove the pressure of timing. Lump sum works better for debt or liquid funds when you have surplus cash sitting idle. Park emergency funds as a lump sum in liquid funds Use monthly SIP for equity funds tied to 7–10 year goals Use Step-up SIP when your salary increases each year Pairing the right investment method with the best mutual fund based on financial goals makes the plan work even when markets do not cooperate. Should You Use Multiple Funds for Multiple Goals? Yes, without question. The best mutual fund based on financial goals is rarely one fund for everything – that approach either under-protects short goals or under-grows long ones. A simple goal-based structure looks like this: Emergency corpus: One liquid fund, fully accessible 5-year down payment: One balanced advantage fund Child’s education in 10 years: One large cap and one mid cap equity fund Retirement in 25 years: One flexi cap fund and one ELSS for Section 80C benefit Each fund has a job. When every fund knows its job, the entire portfolio runs cleaner. That is what choosing the best mutual fund based on financial goals actually looks like in practice. Explore our Mutual Funds services to compare fund categories, evaluate risk levels, and build an investment portfolio aligned with your financial goals. Frequently Asked Questions Q1. How do I start choosing the best mutual fund based on financial goals with no prior experience? Define your goal and timeline first. Then pick the matching fund category – liquid
Top Performing Mutual Funds in India Based on 5-Year Returns
The top performing mutual funds in India based on 5-year returns are Quant Small Cap Fund (33.6% CAGR), Nippon India Small Cap Fund (21.2% CAGR), Motilal Oswal Midcap Fund (22.4% CAGR), HDFC Mid-Cap Opportunities Fund (20.5% CAGR), and Parag Parikh Flexi Cap Fund (22.3% CAGR) – data as of late 2025. Now here is something worth thinking about. A friend of mine from Jaipur – government job, fixed salary – started putting Rs 5,000 every month into a small cap fund back in 2019. No stock market knowledge. No financial background. Just a SIP and patience. When COVID hit in 2020, his portfolio went down by almost 40%. His wife asked him to stop. He did not. Three years later, that same portfolio had recovered fully and then some. By 2024, it had more than doubled. He did not do anything special. He just chose one of the top performing mutual funds in India and refused to blink. Which Are the Top Performing Mutual Funds in India Right Now? The top performing mutual funds in India, based on 5-year CAGR as of late 2025, are listed below. These figures are for Direct Plans, which always give better returns than Regular Plans because there is no middleman commission eating into your growth. Fund Name Category 5-Year CAGR (Approx.) Risk Level Quant Small Cap Fund Small Cap 33.6% Very High Nippon India Small Cap Fund Small Cap 21.2% Very High Motilal Oswal Midcap Fund Mid Cap 22.4% High HDFC Mid-Cap Opportunities Fund Mid Cap 20.5% High Parag Parikh Flexi Cap Fund Flexi Cap 22.3% Moderate-High HDFC Flexi Cap Fund Flexi Cap 17.6% Moderate-High Returns are approximate, based on direct plan data as of late 2025. Past performance does not guarantee future results. Verify current returns before investing. What makes these top performing mutual funds in India stand out is not one big year. It is that they showed up consistently – good market, bad market, sideways market – year after year. Why Do 5-Year Returns Tell the Real Story About Top Performing Mutual Funds in India? A 5-year return window separates genuine performers from lucky ones. Any fund can have a great year. A sector catches fire, stocks run up, and suddenly the fund looks like a genius. But stretch that to five years and the picture changes completely. You see how it handled the COVID crash. You see how it recovered in 2021. You see how it held up when markets corrected in late 2022 and again in 2024. The top performing mutual funds in India on this list went through all of that. They did not just survive those periods – they came out ahead of their benchmarks. That is the only proof that actually matters. What Types of Funds Are Among the Top Performing Mutual Funds in India? The top performing mutual funds in India sit across three main categories – and each one is built for a different kind of investor. Small Cap Funds These are the high-octane ones. Quant Small Cap and Nippon India Small Cap have delivered the strongest 5-year numbers. But they also fall the hardest when markets turn bad. If you check your portfolio every day and feel anxious when it drops, small-cap funds will give you sleepless nights. They are best for someone who can truly stay put for 7 to 10 years without touching the money. Mid Cap Funds HDFC Mid-Cap Opportunities and Motilal Oswal Midcap sit right in the middle – better growth potential than large caps, slightly less rollercoaster ride than small caps. For a working professional in their 30s building long-term wealth, mid-cap funds from this list of top performing mutual funds in India are often the sweet spot. Flexi Cap Funds Parag Parikh Flexi Cap Fund is genuinely different from others in this category. It holds Indian stocks across all sizes and also invests a portion in international companies. When Indian markets are overvalued, the fund manager can park more money abroad. That flexibility has kept it steady through multiple market cycles, which is exactly why it keeps appearing on every serious list of top performing mutual funds in India. How Should You Actually Choose From the Top Performing Mutual Funds in India? Do not pick a fund because it topped a list. Pick it because it matches where you are in life right now. A 27-year-old with no dependents and a stable job can take more risk – small cap makes sense. A 42-year-old with a home loan, school fees, and retirement ten years away needs something steadier – flexi cap or mid cap fits better. Before putting money into any of these top performing mutual funds in India, answer these three questions: How long can I stay invested without needing this money back? What is the maximum portfolio drop I can handle without panicking? Am I picking Direct Plan – or am I unknowingly paying extra commission through a Regular Plan? That last point alone can save you Rs 3 to 5 lakh over a 10-year SIP, just by switching to Direct. Most people do not even know they are on a Regular Plan. Platforms like R9wealth.com show you side-by-side comparisons of top performing mutual funds in India – with 5-year CAGR, rolling returns, expense ratios, and risk ratings all in one place – so you are not flying blind when you decide. Can a Monthly SIP in Top Performing Mutual Funds in India Actually Change Your Financial Life? Yes – and the math is not even close. Rs 10,000 per month in a fund with 25% CAGR over 10 years compounds to roughly Rs 1.1 crore. That same Rs 10,000 per month sitting in a bank FD at 7% gives you around Rs 17 lakh over the same period. That is not a small gap. That is a completely different quality of life at retirement. The top performing mutual funds in India make this possible for ordinary salaried people – teachers, engineers, shopkeepers, government
Why Large Cap Mutual Funds Are the Safest Starting Point for New Investors
Starting your investment journey is exciting. But it is also confusing. Everyone has an opinion. Someone says go for small cap for high returns. Someone else says index funds are the only way. Your colleague swears by some random mid cap fund that gave 40 percent last year. Cut through all that noise and one thing becomes clear pretty quickly. For someone who is new to investing, large cap mutual funds are almost always the most sensible place to begin. Not because they are the most exciting option. But because they are reliable, they are stable, and they do not punish you badly for being a beginner. What Large Cap Actually Means SEBI defines large cap companies as the top 100 companies on Indian stock exchanges by market capitalisation. These are names most Indians already know – Reliance, HDFC Bank, Infosys, TCS, ITC, Hindustan Unilever. These companies have been around for decades. They have strong balance sheets, experienced management teams, and established market positions. They are not going to disappear overnight because of one bad quarter or one difficult year in the economy. Large cap mutual funds invest at least 80 percent of their assets in these top 100 companies. So when you invest in large cap mutual funds, your money is going into some of the most solid businesses in the country. Why New Investors Struggle With Other Fund Types Before getting into why large cap mutual funds work well, it helps to understand why other options are harder for beginners. Small cap funds can give impressive returns but they also drop sharply during bad markets. A beginner who sees their investment fall 35 percent in a few months will almost certainly panic and exit – locking in losses that would have recovered if they had just stayed put. Mid cap funds are better but still volatile enough to make new investors nervous during market downturns. Even flexi cap funds, which sound flexible and safe, can move aggressively depending on where the fund manager allocates money. Large cap mutual funds do not eliminate risk. No investment does. But the swings are noticeably smaller and that makes it much easier for a new investor to stay calm and stay invested. The Stability Factor Is a Real Advantage When markets fall – and they do fall, sometimes significantly – large cap stocks hold up better than small or mid cap stocks. The reason is straightforward. Large companies have more resources to weather difficult periods. They have cash reserves, diversified revenue streams, and the ability to cut costs when needed. Investors also trust them more during uncertain times, which means less panic selling of large cap stocks compared to smaller ones. For a beginner, this stability is genuinely valuable. Watching your portfolio drop 10 percent feels very different from watching it drop 30 percent. Large cap mutual funds tend to limit how bad the bad periods actually feel, which keeps new investors from making emotional decisions at the wrong time. Consistent Returns Without Drama Large cap mutual funds are not going to give you 60 percent returns in a single year. That is also not really what they are for. What they do give you is steady, relatively predictable growth over time. The Nifty 50 – which tracks the top 50 large cap companies – has delivered around 12 to 14 percent average annual returns over long periods historically. That kind of return, compounded over ten or fifteen years, creates serious wealth. The absence of drama is actually a feature for beginners. You are building the habit of staying invested, understanding how markets move, and growing your confidence as an investor. Large cap mutual funds let you do all of that without the stress of extreme volatility pulling you in the wrong direction. Specific Reasons Large Cap Mutual Funds Work for New Investors Here is what makes them genuinely beginner-friendly: The underlying companies are well-known and easier to understand and trust Lower volatility means less emotional stress during market downturns Long track records make it easier to study past performance before investing Fund managers have more data and analyst coverage on large cap stocks, which generally leads to better-informed decisions Liquidity is high – large cap stocks trade in huge volumes, so buying and selling within the fund is smooth Expense ratios on large cap mutual funds tend to be lower than actively managed small or mid cap funds Recovery after market falls tends to happen faster compared to smaller company funds Each of these points matters more for a new investor than for someone who has been through multiple market cycles already. How to Get Started With Large Cap Mutual Funds Starting is simpler than most people think. Pick a platform – Groww, Kuvera, Zerodha Coin, and MF Central are all beginner-friendly and free to use. Complete your KYC with your PAN card and bank details. Choose a large cap mutual fund with a consistent three to five year track record and a low expense ratio. Set up a monthly SIP – even 500 or 1000 rupees works to start. Some large cap mutual funds worth researching include Mirae Asset Large Cap Fund, HDFC Top 100 Fund, Axis Bluechip Fund, and ICICI Prudential Bluechip Fund. These have solid histories and are widely followed. Always verify current performance and ratings before making a decision. After setting up your SIP, the most important thing is to leave it alone. Do not stop it when markets fall. Do not increase it dramatically after one good month. Consistency is what makes large cap mutual funds work over time. Explore our Large Cap Mutual Funds solutions to build a stable investment foundation with established companies and long-term growth potential. FAQs Q1. Are large cap mutual funds completely safe? No investment is completely safe. But large cap mutual funds are among the least volatile options in the mutual fund space. For a beginner, they are a much calmer starting point than most alternatives. Q2. How long
How Risky Are Small Cap Mutual Funds and How to Manage That Risk
Small cap mutual funds have a reputation. Ask anyone who has been investing for a few years and they will tell you – these funds can make you good money but they can also give you some really uncomfortable months along the way. That reputation is not wrong. Small cap mutual funds are genuinely riskier than large cap or mid cap options. But risky does not mean bad. It means you need to understand what you are getting into before you put your money in. What Makes Small Cap Companies Different SEBI defines small cap companies as those ranked 251 and beyond on Indian stock exchanges by market capitalisation. These are smaller businesses – not household names, not companies that have been around for fifty years with thousands of employees. Some of these companies are growing fast. Some are struggling. Some will become massive in ten years. Others will not survive. That uncertainty is the core of what makes small cap mutual funds carry more risk than other categories. When you invest in small cap mutual funds, your money goes into a pool that buys shares of these smaller companies. If many of them do well, your returns are strong. If the market turns and investors panic, small cap stocks fall fast and hard – often much more than large cap stocks do. The Real Risks Inside Small Cap Mutual Funds Understanding the specific risks helps a lot. These are not abstract dangers – they are actual patterns that happen repeatedly in the market. Liquidity Risk Small cap stocks do not trade in huge volumes every day. When a fund manager needs to sell a large chunk of a small cap stock quickly – say, during a market crash when everyone is redeeming their investments – it becomes difficult. Selling in a low-volume market often means accepting a lower price. That hurts the fund’s NAV and your returns along with it. Volatility Risk Small cap mutual funds swing much more dramatically than other fund types. A fund that gave 40 percent returns one year can easily go negative 30 percent the next year. That kind of movement is hard to sit through, especially for someone who is new to investing and watching their portfolio value drop every week. Business Risk Smaller companies are more vulnerable to bad management decisions, sectoral downturns, or just plain bad luck. A large company like an HDFC or Infosys can absorb a tough year much better than a small company can. When multiple companies in a small cap fund face business trouble at the same time, the fund takes a serious hit. Market Sentiment Risk When investors get nervous – geopolitical tension, rising inflation, global recession fears – they exit riskier assets first. Small cap stocks are almost always the first to get sold. This means small cap mutual funds can drop sharply even when the underlying companies are doing perfectly fine as businesses. So Why Do People Still Invest in Small Cap Mutual Funds Because the returns over a long period have been genuinely impressive. Small cap mutual funds have historically outperformed large cap and mid cap funds over a ten-year-plus horizon. The reason is simple – smaller companies have more room to grow. A company worth 500 crore can become worth 5000 crore in a decade. A company already worth 5 lakh crore does not have that kind of growth headroom. The risk and the return potential are two sides of the same coin with small cap mutual funds. You cannot have the upside without accepting the downside. How to Actually Manage the Risk This is where most beginners go wrong. They either avoid small cap mutual funds completely out of fear or they invest too heavily without understanding what they signed up for. Both approaches have problems. Here is what actually works: Keep your small cap allocation limited – Most financial advisors suggest keeping small cap mutual funds at 10 to 20 percent of your total portfolio. The rest should be in more stable options like large cap or index funds. Use SIP, not lump sum – Putting everything in at once is a bad idea with small cap mutual funds. SIP spreads your investment over months and years, which smooths out the impact of volatility through rupee cost averaging. Set a minimum time horizon of eight to ten years – Small cap mutual funds need time to recover from bad periods and deliver their real potential. Investing for three or four years and expecting magic is unrealistic. Do not check your portfolio every week – Watching a small cap fund drop 15 percent in a month and not reacting badly requires discipline. Checking less frequently makes that discipline much easier to maintain. Pick funds with experienced managers – Not all small cap mutual funds are managed the same way. Funds with experienced managers who have steered through at least one full market cycle tend to be more reliable choices. Diversify within small caps too – A well-managed small cap fund already holds 50 to 70 companies across sectors. That internal diversification reduces the damage any single company can do. What Beginners Should Remember Most Small cap mutual funds are not for everyone. They are not for someone who needs the money in two years. They are not for someone who will panic and exit when the fund drops 25 percent. But for someone who is young, has time on their side, and can genuinely stay invested through the uncomfortable periods – small cap mutual funds can be a powerful part of building long-term wealth. The risk is real. Managing it is not complicated. You just need patience and a clear head about why you invested in the first place. Explore our Small Cap Mutual Funds solutions to understand high-growth investment opportunities and strategies for managing long-term risk. FAQs Q1. Are small cap mutual funds safe for beginners? They carry more risk than large or mid cap funds. Beginners can invest
How Mid Cap Mutual Funds Work and Why Beginners Should Know About Them
When people start investing, they usually hear about large-cap funds first. Safe, stable, reliable. Then someone mentions small cap, and suddenly the conversation gets exciting but also a little scary. Mid-cap mutual funds sit right between these two, and honestly, they do not get talked about enough – especially for beginners. Understanding mid-cap mutual funds is actually not complicated. And knowing how they work can seriously change how you build your investment portfolio over time. What Does Mid Cap Even Mean Before anything else, the term needs a quick explanation. SEBI – the market regulator in India – defines mid-cap companies as those ranked between 101 and 250 on the stock exchange based on market capitalisation. So these are not the biggest companies like Reliance or TCS. They are also not tiny, unknown startups. They sit in the middle – companies that are established enough to have a track record but still have significant room to grow. Mid-cap mutual funds invest primarily in these companies. At least 65 percent of the fund’s total assets go into mid-cap stocks as per SEBI rules. The rest can go into large cap or small cap, depending on the fund manager’s strategy. How Mid Cap Mutual Funds Actually Work You put money into the fund. The fund manager pools that money with investments from thousands of other people. That pool then gets invested into shares of mid-cap companies across different sectors – manufacturing, technology, healthcare, consumer goods, and so on. As these companies grow and their stock prices rise, the value of your investment grows too. You get units of the fund when you invest. The more the NAV – Net Asset Value – of those units, the more your money is worth. Mid cap mutual funds are actively managed in most cases. That means a fund manager and their team are constantly researching companies, watching market trends, and deciding which mid-cap stocks to hold or exit. You are basically paying a small fee – called the expense ratio – for that expertise. Why Mid Cap Mutual Funds Are Worth Knowing About Here is the thing about mid-cap companies. They are past the very risky early stage. They have products, customers, and revenues. But they have not yet hit their peak growth. That growth potential is exactly what makes mid cap mutual funds attractive. Historically, mid cap funds have delivered higher returns than large cap funds over a long period. The trade-off is that they also come with higher volatility. When the market falls, mid cap stocks tend to fall more sharply than large cap stocks. When the market recovers, they also tend to bounce back stronger. For someone who can stay invested for seven to ten years and not panic during market dips, mid cap mutual funds can be a very rewarding part of the portfolio. Who Should Actually Consider Mid Cap Mutual Funds Not everyone. And that is an important thing to say upfront. Mid cap mutual funds work well for: Investors who already have some large-cap or index fund exposure and want to add growth potential People with a long investment horizon – at least seven years ideally Those who understand that short-term volatility is part of the process Beginners who are willing to start small through SIP and not touch the investment for years Anyone looking to build wealth over the long term rather than make quick gains If you are investing for a goal that is two or three years away, mid cap mutual funds are probably not the right fit. The time horizon matters a lot with these funds. Best Ways to Invest in Mid Cap Mutual Funds as a Beginner Starting through SIP is the smartest approach. You invest a fixed amount every month – 500, 1000, 2000 rupees, whatever fits your budget. This removes the pressure of timing the market perfectly. When markets fall, your SIP buys more units at lower prices. When markets rise, your existing units are worth more. Over a long period, this averaging works in your favour in a very real way. Some mid cap mutual funds that have shown consistent long-term performance in India include: Kotak Emerging Equity Fund – well-diversified across mid cap companies with a strong track record Nippon India Growth Fund – one of the older mid cap funds with a reliable history HDFC Mid-Cap Opportunities Fund – large AUM and consistent performance over multiple market cycles Axis Midcap Fund – known for quality stock selection within the mid cap space DSP Midcap Fund – good diversification with a research-driven approach These are not recommendations. Always check current performance, expense ratio, and your own risk profile before investing in any mid cap mutual funds. One Thing Beginners Often Get Wrong They see mid cap mutual funds delivering 18 or 20 percent returns in one good year and expect that every year. That is not how it works. Some years mid cap funds will give very strong returns. Other years they will be negative. The average over a long period is what matters. Expecting consistent double-digit returns every year leads to disappointment and bad decisions – like exiting the fund at exactly the wrong time. Stay invested. Do not check your portfolio every week. Let the fund do its job over years. FAQs Q1. Are mid cap mutual funds good for beginners? They can be, yes – but only if you have a long time horizon and can handle some volatility without panicking. Start with a SIP and keep your expectations realistic. Q2. How long should I stay invested in mid cap mutual funds? At least seven years. Ideally ten or more. These funds need time to actually deliver their potential returns. Q3. What is the minimum amount to invest in mid cap mutual funds? Most funds allow SIP starting at 500 rupees per month. Some go as low as 100 rupees. There is no reason to wait until you have a large amount. Q4. Are mid cap
Best Mutual Funds to Invest in for Beginners in India 2026
Starting to invest feels overwhelming for most people. Not because it is actually that hard, but because everyone around you uses terms like NAV, expense ratio, and exit load, and you just sit there nodding without a clue what any of it means. Good news – you do not need to understand all of that to get started. You just need to know a few basics, pick decent mutual funds to invest in, and stay consistent. That is genuinely all there is to it at the beginning. Why Mutual Funds Make Sense for Beginners Picking individual stocks is risky. Most beginners who try it end up losing money. Mutual funds take away that pressure completely. Your money goes into a pool with thousands of other investors. A professional fund manager decides where that pool gets invested – stocks, bonds, government securities, or a mix. You get units in return. As the investments grow, your units become worth more. You are not timing the market. You are not tracking fifteen different companies. You are just letting a system work while you go on with your life. That is a pretty decent deal for someone who is new to this. Starting Small Is Completely Fine A lot of people think they need a large sum to start investing. That is not how mutual funds work in India. SIP – Systematic Investment Plan – lets you put in a fixed amount every month. Some funds accept as little as 100 rupees a month. Most beginners start somewhere between 500 and 2000 rupees monthly. The amount matters less than the habit. Someone putting in 1000 rupees every month for ten years will almost always do better than someone waiting to have a large lump sum ready. Starting small and staying consistent beats waiting every single time. The Types Worth Knowing Before You Pick Anything There are many categories of mutual funds but beginners really only need to understand three or four to make a decent choice. Index Funds These track a market index – usually the Nifty 50 or Sensex. They do not depend on a fund manager making smart calls. They just follow the index up and down. Lower fees, simple structure, and solid long-term returns. Many people who have been investing for years still recommend index funds as the best mutual funds to invest in for beginners. Large Cap Equity Funds These put your money into big, well-established companies – the kind that have been around for decades and are unlikely to disappear overnight. More stable than small or mid-cap funds. Good if you want equity exposure without too much volatility. Hybrid Funds Part equity, part debt. The fund automatically balances the two based on market conditions. If you are not sure how much risk you can handle, a hybrid fund is a comfortable middle ground. Not too aggressive, not too conservative. Debt Funds Invest in bonds and government securities. Very low risk compared to equity. Not going to make you rich fast, but also not going to give you sleepless nights. Good for shorter-term goals – one to three years. Specific Funds Worth Looking At in 2026 These are not random picks. These have shown consistent performance and are genuinely appropriate for someone just starting: Nifty 50 Index Fund by UTI or Nippon – Simple, low cost, and tracks the top 50 Indian companies. A very solid first choice for mutual funds to invest in. Mirae Asset Large Cap Fund – Has a strong track record across market cycles. Good for a five-plus year horizon. HDFC Balanced Advantage Fund – A hybrid fund that manages the equity-debt ratio on its own. Less decision-making for you. Parag Parikh Flexi Cap Fund – Invests across company sizes and includes some international stocks. Good diversification without complexity. SBI Magnum Gilt Fund – Government securities only. As safe as a mutual fund gets. Good for conservative beginners. None of these is guaranteed to perform the same way in the future. But they have been managed well and are transparent in their approach – which matters a lot when you are just getting started. One Mistake Almost Every Beginner Makes When the market falls – and it will fall sometimes – most new investors panic and stop their SIP or withdraw their money. That is the worst possible move. When markets fall, your monthly SIP buys more units at lower prices. Over time, when the market recovers, those extra units you accumulated during the dip are worth significantly more. This concept is called rupee cost averaging, and it only works if you do not stop investing when things look bad. The people who stay put during downturns are usually the ones who end up with the best returns five or ten years later. Where to Actually Buy These Funds You do not need to walk into a bank branch or call a broker. Everything is online now. Groww, Kuvera, Zerodha Coin, and MF Central are all clean, beginner-friendly platforms. You need your PAN card and bank account details. Setup takes around fifteen to twenty minutes. After that, setting up a SIP is just a few taps. Direct plans – where you buy directly without a broker in between – have lower expense ratios than regular plans. Always pick direct plans on these platforms. The difference in returns over ten years is noticeable. Explore our Mutual Funds services to discover investment options, SIP planning, and expert guidance for building long-term wealth. FAQs Q1. How much should a beginner invest in mutual funds every month? Whatever amount you will not miss from your monthly budget. Even 500 rupees works. The habit matters more than the amount when you are starting out. Q2. Is it safe to invest in mutual funds in India? There is always some risk, especially with equity funds. But if you stay invested for the long term and do not panic during dips, the risk reduces quite a bit over time. Q3. Index fund