Benefits and Risks of Equity Mutual Fund Schemes
Learn about the benefits and risks of Equity Mutual Fund Schemes before you invest.
How Much to Invest in Mutual Funds
Not sure how much to invest in mutual funds? Find the right SIP amount for your goals.
Gold Mutual Funds: A Safe Haven in Volatile Markets?
Compare gold mutual funds in India, understand the risks and find the best option for your portfolio.
Bandhan Large Cap Fund: A Complete Growth and Investment Guide
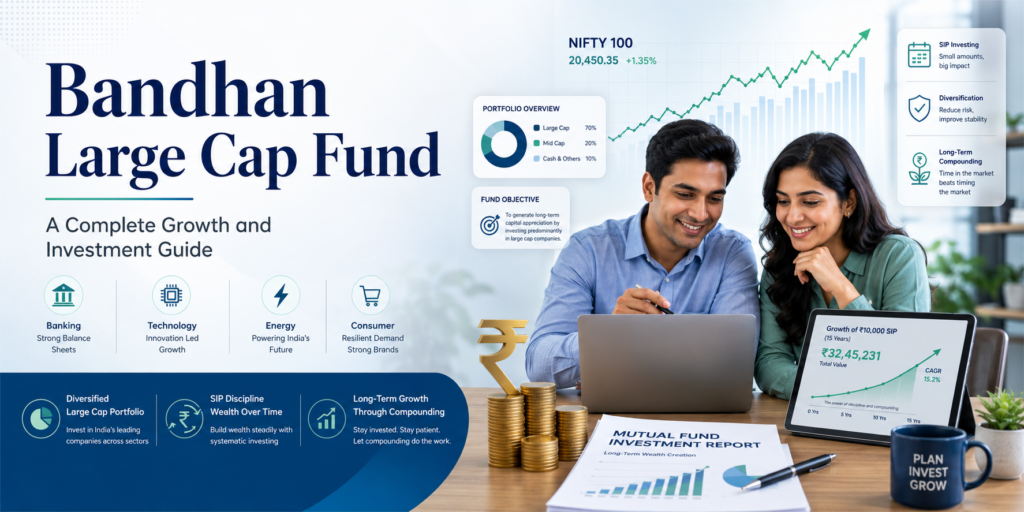
Explore Bandhan Large Cap Fund, its SIP, growth potential, risks and how to start investing.
Best Large Cap Mutual Funds in India (2026)
Looking for the best large cap mutual funds in India? Discover smart picks and invest with confidence.
Gold Mutual Funds vs Physical Gold: Which Is Better for Modern Investors?
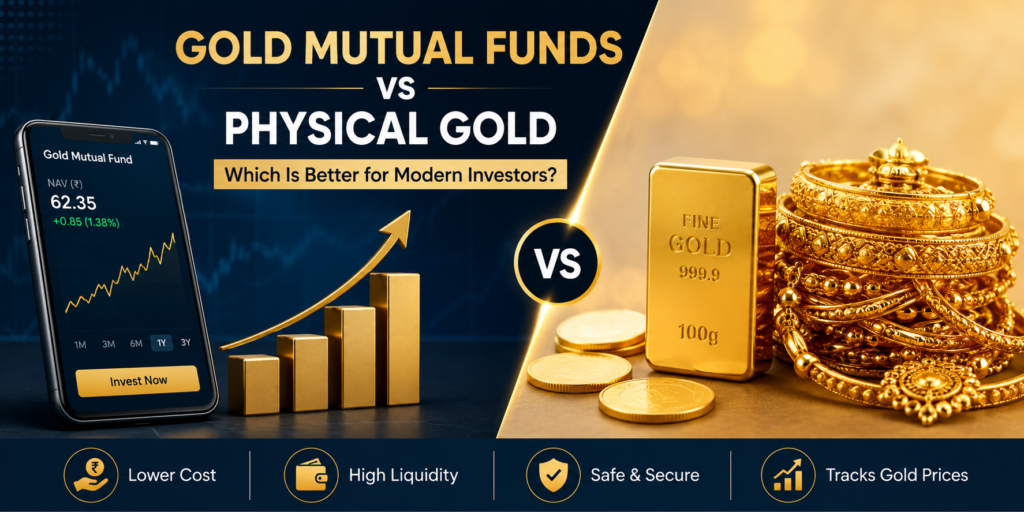
Gold mutual funds vs physical gold: discover costs, returns, risks, and which option suits modern investors best.
What Factors Affect Mutual Fund Returns and How to Evaluate Them
No two mutual funds grow the same way, and that comes down to the Factors Affect Mutual Fund Returns behind every scheme. Some funds shoot up in a good year and stumble the next. The difference traces back to a handful of forces working together, and once you know them, a fund’s performance stops feeling like a mystery. This blog walks through the Factors Affect Mutual Fund Returns one by one, so you can judge a fund before investing. What Are the Main Factors Affect Mutual Fund Returns? Four things drive most of the outcomes: the market, the fund manager, the cost structure, and how money is split across assets. These are the core Factors Affect Mutual Fund Returns, and none work in isolation. A quick breakdown: Market performance sets the ceiling on possible growth The fund manager decides which stocks or bonds enter the portfolio Expense ratio quietly eats into whatever the fund earns Asset allocation determines how much risk is really being taken Once you separate these Factors Affect Mutual Fund Returns, comparing two funds becomes far easier. How Do Market Factors Affect Mutual Fund Returns? The market is the loudest voice in the room. Prices rise and fall, and mutual funds ride that wave whether they want to or not. A few points worth noting: Equity-heavy funds swing harder when the market moves Debt funds stay calmer, though not fully immune Staying invested longer smooths out the bumps Nobody can predict the market with certainty, which is why it remains the hardest of the Factors Affect Mutual Fund Returns to control. How Do Expense Ratio Factors Affect Mutual Fund Returns? Every fund charges a fee for managing your money, called the expense ratio. It looks small, maybe 1 or 2 percent, but it adds up year after year. Take a fund earning 12 percent annually. With a 2 percent expense ratio, the investor keeps only 10 percent. That gap widens over time, so cost deserves as much attention as returns among the Factors Affect Mutual Fund Returns. How Do Fund Manager Factors Affect Mutual Fund Returns? A fund manager is not picking stocks at random. Their calls on timing, sector exposure, and exit points shape the outcome. What a good manager typically does: Builds a portfolio that fits the fund’s stated goal Rebalances holdings when conditions shift Cuts losses early instead of waiting Track record matters here, and it is one of the more human Factors Affect Mutual Fund Returns since judgment plays such a big role. Which Economic Factors Affect Mutual Fund Returns the Most? Step outside any single fund and you run into forces no fund manager controls: interest rates, inflation, and the pace of economic growth. A rate hike or a bad inflation print can move an entire category, not just one scheme. Here is a quick way to see how each one plays out: Economic Factor Impact on Returns Fund Type Most Affected Interest Rate Changes Rising rates pull bond prices down Debt Funds Inflation Eats into the real value of gains Equity and Debt Funds GDP Growth Fuels stronger company earnings Equity Funds Currency Fluctuation Swings the value of overseas holdings International Funds Most investors never check these numbers directly, yet they sit behind nearly every news headline about the Factors Affect Mutual Fund Returns. How Do Asset Allocation Factors Affect Mutual Fund Returns? How money is split between equity, debt, and other instruments decides how much risk an investor carries. Broadly, investors pick one of three paths: Aggressive, with heavy equity exposure for higher growth Balanced, mixing equity and debt to manage swings Conservative, leaning mostly on debt for stability Unlike market movement, this is one of the Factors Affect Mutual Fund Returns an investor can control from day one. How Can You Evaluate the Factors Affect Mutual Fund Returns Before Investing? Evaluation is not complicated once you know what to check: past performance, cost, manager history, and how much risk you can stomach. A practical checklist: Look at returns over 3, 5, and 10 years, not just one Compare the expense ratio against similar funds Check how long the current fund manager has been in charge Be honest about your own risk appetite before choosing Weighing these Factors Affect Mutual Fund Returns together, rather than picking one number, separates a rushed decision from a sound one. For a structured walkthrough, r9wealth.com/mutual-fund covers this in more depth. Want to choose the right mutual fund? Explore R9 Wealth’s Mutual Fund solutions to compare investment options and build a portfolio aligned with your financial goals Frequently Asked Questions 1. What are the biggest Factors Affect Mutual Fund Returns? Market movement, expense ratio, fund manager skill, and asset allocation carry the most weight. 2. Does inflation affect mutual fund returns? Yes, it reduces the real value of whatever the fund earns over time. 3. How often should I check mutual fund performance? Once every six months is usually enough to track consistency without overreacting. 4. Can the expense ratio reduce my actual returns? Yes, a higher expense ratio directly lowers what an investor takes home each year. 5. Is market volatility always bad for mutual funds? Not really. Investors who stay invested longer usually ride out short-term dips fine. Follow us on Instagram, LinkedIn , Facebook, and X (Twitter) for expert mutual fund insights, investment tips, and the latest financial updates.
What Is SWP in Mutual Funds? A Beginner’s Guide
A Systematic Withdrawal Plan, or SWP in Mutual Funds, lets you pull a fixed amount out of your mutual fund holdings at regular intervals, rather than redeeming everything in one shot. Here’s how it actually works, who it makes sense for, and what to weigh before you set one up. The Basic Idea Think of it as a SIP running backward. A SIP builds up your savings by feeding in small amounts every month. An SWP does the opposite – it draws small amounts out of a pot of money you’ve already built. Say you’ve got ₹30 lakh sitting in a fund and want ₹15,000 a month out of it. You set that up once, and the payments keep landing in your account until you decide to change the amount or stop altogether. Here’s the mechanics: you invest a lump sum upfront, choose how much you want withdrawn and how often, and on each due date, the fund quietly sells off just enough units to cover that payout. The cash lands in your bank account; everything else stays invested and keeps working. It’s a favorite among retired professionals in India for exactly this reason – it feels like a salary, without forcing you to liquidate your entire nest egg at once. How the Mechanics Play Out There’s nothing mysterious about it. Each cycle, the fund redeems a slice of your units – never the whole investment – on a date you’ve fixed in advance. You start by putting a lump sum into a scheme of your choice. Then you pick a number, say ₹10,000 a month, and a frequency. When the due date rolls around, the fund house sells off enough units to cover that amount, and the money typically shows up in your bank account within two or three days. Whatever’s left behind doesn’t just sit there – it stays exposed to the market, rising some months and dipping in others. That’s really the one thing separating this from something like a fixed deposit: the balance isn’t frozen; it’s still moving. Who Actually Benefits From This It’s not for everyone. It suits people who need money coming in on a schedule but don’t have a paycheck doing that job for them. Retirees are the obvious fit – the salary’s gone, but the electricity bill isn’t. Freelancers with unpredictable income sometimes use it too, as a way to smooth out the lean months. And there’s a smaller group who just like the discipline of it – a scheduled payout keeps them from raiding their principal on a whim. Why People Choose It The real draw is that it doesn’t ask you to pick between earning income and growing your money – you get a bit of both, just spread out over time. Tax treatment is a big part of the appeal. Only the gain component of each withdrawal gets taxed, not the whole payout – unlike, say, interest income, which is taxed in full. It’s also flexible: you can change the withdrawal amount or frequency whenever your situation shifts, there’s no lock-in period to work around, and stopping the plan entirely doesn’t cost you a penalty. SWP vs. Fixed Deposit – Which Wins? That really comes down to whether you value certainty or efficiency more. A fixed deposit gives you a guaranteed payout, full stop – no surprises, no market risk. An SWP trades that certainty away, but it usually makes up for it through better tax treatment and by letting the rest of your money keep growing instead of sitting flat. Feature SWP in Mutual Funds Fixed Deposit Return Type Market-linked, can vary Fixed and guaranteed Tax Treatment Only capital gains are taxed Full interest is taxable Liquidity Flexible – pause or change anytime Early exit usually incurs a penalty Risk Level Moderate, depends on fund type Low Growth Potential The remaining corpus keeps growing Capped by the interest rate If you’re comfortable riding out some market ups and downs, an SWP tends to come out ahead over the long run – especially once you factor in the tax savings. Setting One Up This is quicker than most people expect. Fund houses and investment apps now handle the entire registration online. Pick a scheme and invest a lump sum Decide how much you want withdrawn and how often Submit the SWP form through the fund’s website or a distributor Link the bank account that should receive the payouts Once that’s in place, the withdrawals just run in the background. Is It Taxable in India? Yes – but not on the full amount you withdraw, which trips up a lot of first-timers. Only the gains portion of each payout is taxed. For equity funds, gains on units held over a year fall under long-term capital gains tax; anything sold sooner is taxed at the short-term rate. Debt funds work differently – the withdrawal gets added to your income and taxed at your regular slab rate. Want expert guidance before starting an SWP? Explore R9 Wealth’s complete Mutual Fund Services to find suitable investment options based on your financial goals and risk profile. Frequently Asked Questions 1. What is the minimum amount needed to start SWP in Mutual Funds? Most schemes accept an initial lump sum of ten to twenty-five thousand rupees, though this varies by fund house. 2. Can an SWP in Mutual Funds be stopped midway? Yes. It can be paused, changed, or stopped at any point, with no penalty in most schemes. 3. Are the returns from SWP in Mutual Funds guaranteed? No. Payouts depend on market performance, unlike a deposit’s fixed interest. 4. Is SWP in Mutual Funds a good fit for retirement income? Yes, it’s one of the more common tools Indian retirees use to build a monthly income stream from savings. 5. What happens if the fund balance runs out during SWP in Mutual Funds? If withdrawals outpace growth for too long, the corpus can shrink to zero – which is why the withdrawal
What Are High Return Mutual Funds in India?
High return mutual funds in India are equity-heavy schemes that put your money into the stock market instead of letting it sit in a savings account. Over the years, they’ve grown wealth faster than FDs, though that growth comes with real ups and downs. Raj, a 28-year-old software engineer from Pune, kept his savings locked in an FD for three years. Then his friend showed him what a mutual fund portfolio had earned in that same window, and the gap honestly stunned him. This isn’t an unusual story. Across India right now, a lot of people are quietly moving money out of FDs because high return mutual funds, given enough time, just perform better. How Do High Return Mutual Funds Work? A fund manager pools money from thousands of investors and buys stocks, bonds, or some mix of both on their behalf. The goal is usually to beat the broader market over time. Money in a savings account doesn’t really do anything. Money in a mutual fund does – it’s moving, rebalancing, reacting to whatever’s happening in the market that week. When the companies in the fund’s portfolio perform well, the fund’s NAV goes up, and so does your investment. Which Types of High Return Mutual Funds Exist in India? Not every fund under this label works the same way, and the risk gap between them can be pretty wide. Here’s a rough breakdown of what’s out there: Equity mutual funds – built for long-term growth through stocks Small-cap funds – chase smaller, fast-growing companies but swing hard Mid-cap funds – sit in between, balancing risk and growth Sectoral funds – bet on one industry, like IT or pharma Flexi-cap funds – spread money across large, mid, and small companies Picking one usually comes down to how much volatility you can actually stomach, not what’s trending on social media. Why Do High Return Mutual Funds Carry More Risk? Equity markets move on news, sentiment, and sometimes nothing at all – that unpredictability is exactly where the risk comes from. A single earnings report or global event can swing prices overnight. So returns from high return mutual funds are never locked in. A fund that gave 18% last year could easily fall short this year, or even dip into the red. That’s also why people who can stay invested for five, ten, or more years tend to do better here. They’re not panic-selling every time the market wobbles. What Returns Can High Return Mutual Funds Actually Offer? Looking at historical data, high return mutual funds in India have averaged somewhere between 12% and 18% a year over long stretches. None of that is promised going forward, though. Fund Type Typical Return Range Risk Level Large-cap funds 10% to 14% Moderate Mid-cap funds 13% to 17% High Small-cap funds 14% to 20% Very High Flexi-cap funds 12% to 16% Moderate to High These numbers come from past cycles, and markets don’t always repeat themselves. How Should Investors Choose High Return Mutual Funds? It mostly comes down to matching the fund’s risk with your own timeline and comfort level. A 25-year-old saving for retirement can take on more risk than someone who needs the money in three years. A few things worth checking before putting money in: How long can you actually leave the money untouched Whether you can handle watching the value drop without panicking The fund manager’s track record across both good and bad years The expense ratio – high fees quietly chip away at returns Spreading investments across a few fund types instead of just one Revisiting these once a year keeps things on track as goals change. Are High Return Mutual Funds Suitable for Beginners? Beginners can start small and still do fine, as long as the fund matches their risk comfort. A Systematic Investment Plan, or SIP, makes this a lot less stressful than dumping in a lump sum. With a SIP, fixed amounts go in every month instead of all at once. Over time, this evens out the highs and lows without anyone needing to time the market perfectly. In cities like Mumbai, Bangalore, and Delhi, more first-time investors are leaning toward SIPs over picking individual stocks – it just feels more manageable. What Should Investors Check Before Investing in High Return Mutual Funds? Past performance matters, but only when you look at it across full market cycles, not just one strong year. A fund that does great in a bull run might fall apart when the market turns. It also helps to actually read where the fund is investing and why. Pages like High return mutual fund explain how mutual fund returns get calculated, which clears up a lot of confusion for newer investors. This article is for general understanding only, not financial advice. Talking to a registered financial advisor before investing still makes sense, since everyone’s situation looks a little different. Frequently Asked Questions What is considered a good return for mutual funds in India? Somewhere between 12% and 15% a year is generally seen as solid for equity mutual funds long-term. Are high return mutual funds safe for short-term goals? Not really – short-term swings can hurt returns, so these work better for longer goals. How much should a beginner invest in mutual funds monthly? Starting with 500 rupees a month through a SIP works fine, and you can increase it later. Do high return mutual funds guarantee profits? No, returns depend on market performance and are never guaranteed, regardless of past numbers. Which mutual fund category gives the highest returns historically? Small-cap funds have shown the strongest historical returns, though they also carry the most risk. Follow us on Instagram, LinkedIn, Facebook and X (Twitter) for the latest mutual fund insights, SIP tips, investment strategies, and personal finance updates.
Best Gold Mutual Funds to Invest in 2026
Best gold mutual funds in 2026 track gold ETFs closely, keep expense ratios low, and carry a steady multi-year history. SBI Gold Fund, Nippon India Gold Savings Fund, HDFC Gold Fund, and ICICI Prudential Regular Gold Savings Fund show up on most shortlists for that reason. Arjun started a small SIP in gold last year, mainly to balance an equity-heavy portfolio. He didn’t expect much from it. Then gold prices kept climbing through 2025 into 2026, and his view shifted. Gold’s had a strong run lately, pulling more retail money toward funds over physical gold. Here’s what matters before picking among the best gold mutual funds out there. What are the best gold mutual funds in India? Best gold mutual funds invest in gold ETFs on your behalf, so you get gold price exposure without holding physical gold or opening a demat account. You’re buying units of a fund that itself owns units of a gold ETF. That structure cuts out physical-gold headaches – storage, purity checks, theft risk. SIPs work fine too, so no lump sum is needed to start. Why Should You Consider the Best Gold Mutual Funds in 2026? Mostly because gold has held up through a stretch of real economic uncertainty. Domestic prices hit record highs in early 2026, which is part of why interest in the best gold mutual funds has picked up as a hedge. A few reasons people are adding gold right now: Inflation and a weaker rupee push gold prices up Central banks have kept adding to their gold reserves Gold often moves opposite to equities, helping during a dip It diversifies a portfolio without needing a demat account Most advisors suggest capping gold around 10–15% of a portfolio – useful, not the centerpiece. Which Are the Best Gold Mutual Funds to Watch in 2026? A few names keep turning up across fund screeners for consistency, low tracking error, and decent fund size – a reasonable place to start with the best gold mutual funds. Fund AMC Known For SBI Gold Fund SBI Mutual Fund Large investor base, long track record Nippon India Gold Savings Fund Nippon India MF High liquidity, consistent performance HDFC Gold Fund HDFC Mutual Fund Backed by India’s largest AMC ICICI Prudential Regular Gold Savings Fund ICICI Prudential MF Long history, low tracking error Kotak Gold Fund Kotak Mahindra MF Low expense ratio among peers Worth comparing expense ratios and tracking error before settling on one – small gaps add up over a few years. How Do You Start a SIP in the best gold mutual funds? Through any mutual fund platform or directly on the AMC’s website, once KYC is done. Many SIPs in these funds start as low as ₹100 to ₹500 a month, so the entry bar is low. Roughly how it goes: Get KYC done if you haven’t already Pick a fund, check its expense ratio Choose lump sum or SIP Set the amount and frequency Link a bank account and confirm Five years or more tends to be the sweet spot for holding gold funds – not a short-term trade. How Are the Best Gold Mutual Funds Taxed? It comes down to the holding period. Past 24 months, gains count as long-term and get taxed at 12.5% without indexation, under current rules. Sell sooner, and the gains get added to your income at your usual slab rate. Tax rules shift with budgets, so check before you redeem. What Risks Come With the Best Gold Mutual Funds? Gold can sit flat, or drop, for long stretches, with no interest or dividend cushioning the wait. Whatever gold itself does, that’s what your returns mirror. A few other things worth flagging: Import duty changes shift domestic gold prices directly Tracking error means returns can drift slightly from gold prices Over long periods, gold has generally trailed equity Buying in at record-high prices can dent near-term gains None of that rules gold out – it just means treating it as one piece of a portfolio, not the entire plan. Are Best Gold Mutual Funds Right for You in 2026? Comes down to your existing mix and how much equity you’re carrying. If equity dominates your portfolio, a small allocation to the best gold mutual funds can take the edge off the volatility. For more on specific schemes and current numbers, R9 Wealth has a breakdown at r9wealth.com. This article is meant for general information, not financial advice. Mutual funds carry market risk – go through scheme documents or speak with an advisor before investing. Frequently Asked Questions What are the best gold mutual funds right now? SBI Gold Fund, Nippon India Gold Savings Fund, and HDFC Gold Fund are commonly shortlisted for low tracking error. Can I start a gold fund SIP with a small amount? Yes – most gold funds allow SIPs from ₹100 to ₹500 a month. How long should I hold gold mutual funds? Five years or more usually works best for riding out price swings. Are gold mutual funds taxed differently from equity funds? Yes, gains beyond 24 months are taxed at 12.5% without indexation under current rules. Do gold mutual funds need a demat account? No – unlike gold ETFs, they can be bought without one. Follow us on Instagram, LinkedIn, Facebook and X (Twitter) for the latest mutual fund insights, SIP tips, investment strategies, and personal finance updates.